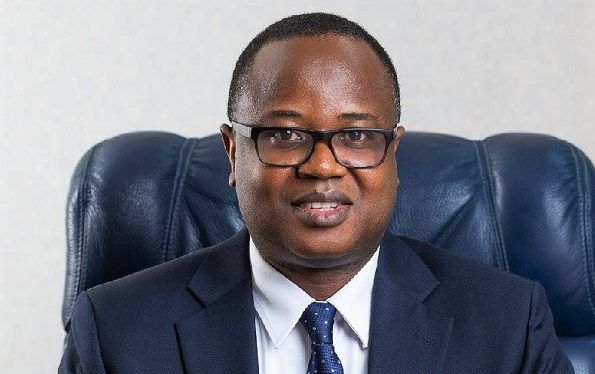

Ghana’s 2022 debt crisis was not a sudden accident but the result of vulnerabilities that had built up over several years, former First Deputy Governor of the Bank of Ghana (BoG), Dr Maxwell Opoku-Afari, has said.
According to Dr Opoku-Afari, persistent fiscal deficits, rising interest costs, weak foreign-exchange reserves and pressure on the cedi were among the warning signs that preceded the crisis.
He said the vulnerabilities were also evident in key sectors including energy, cocoa and financial services, but corrective measures were not implemented with sufficient speed or depth.
Dr Opoku-Afari made the observations in a policy paper titled “How Not to Miss a Crisis: Lessons from Ghana”, published by the Finance for Development Lab, where he currently serves as a Non-Resident Fellow.
Domestic weaknesses drove the crisis
While external shocks and tighter global financial conditions accelerated Ghana’s economic difficulties, Dr Opoku-Afari argued that many of the underlying problems were domestic.
He pointed to weak domestic revenue mobilisation, procyclical spending, rising interest costs and repeated borrowing to finance recurrent expenditure.
He also noted that strong headline economic growth, driven largely by commodities and extractive industries, masked underlying weaknesses including low productivity, limited economic diversification and what he described as “jobs-lite” growth.
At the same time, contingent liabilities and arrears accumulated through state-owned enterprises (SOEs), special-purpose vehicles, quasi-fiscal operations and financial-sector interventions.
Domestic borrowing increased risks
Dr Opoku-Afari also argued that Ghana’s increasing reliance on domestic borrowing, which was partly presented as a move towards de-dollarisation and deeper domestic financial markets, ultimately increased the country’s exposure to risk.
According to him, high domestic interest rates crowded out private-sector credit while strengthening the link between the sovereign and domestic banks.
The significant participation of non-resident investors in cedi-denominated instruments also meant that capital-flow and exchange-rate shocks could quickly affect the domestic financial system.
This, he said, blurred the distinction between domestic and external risks.
Once investor confidence deteriorated and Ghana lost access to international capital markets, the adjustment became sudden and costly.
The resulting crisis eventually led to debt restructuring and significant spillovers across banks, pension funds, businesses and households.
Weak institutions compounded vulnerabilities
Dr Opoku-Afari said the crisis also exposed weaknesses in Ghana’s domestic institutions and external economic surveillance.
He argued that although fiscal rules existed, their enforcement was inadequate.
Debt reporting had improved but did not consistently capture arrears, government guarantees, risks associated with state-owned enterprises and other public-sector balance-sheet exposures.
He also identified weaknesses in oversight, saying Parliament, accountability institutions and civil society did not always have sufficient information, authority or incentives to impose timely fiscal discipline.
International surveillance, he added, had repeatedly classified Ghana as being at high risk, but programme design and assessment did not adequately incorporate rollover and liquidity risks, the interaction between domestic debt and banks, and broader public-sector balance-sheet vulnerabilities.
Lessons for developing economies
Dr Opoku-Afari said Ghana’s experience provides important lessons for other developing and frontier economies.
He argued that a country can maintain strong economic growth, apparently manageable headline debt levels and continued access to financial markets while underlying debt quality and liquidity risks deteriorate.
He therefore called for policymakers to look beyond the overall size of public debt and examine the broader public-sector balance sheet.
The former BoG official said policymakers must also pay closer attention to liquidity risks, domestic financial-sector linkages and the enforcement of fiscal rules.
According to him, Ghana’s experience demonstrates that warning signs of a debt crisis can become visible years before a crisis occurs.
The key challenge, he said, is ensuring that those warning signs trigger corrective action while governments still have the abicanand when to adjust.